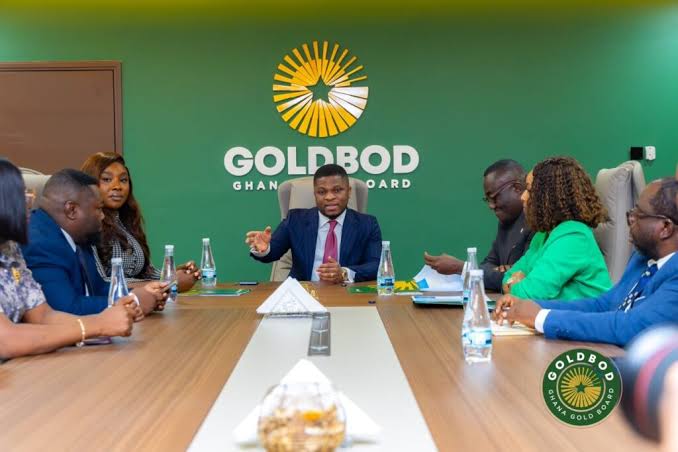
The detailed trade report released by GoldBod outlines total financial inflows of GH¢133.26 billion during the 2025 operating period. Out of this total inflow, the expected value of gold scheduled for delivery to the central bank stood at GH¢132.29 billion. However, the value of actual gold delivered to the Bank of Ghana reached GH¢128.55 billion, representing an aggregate volume of 80,762.55 kilogrammes of gold.
This variance resulted in a net figure of GH¢3.78 billion listed under the report's column for over-supplies, under-supplies, and undistributed funds payable to the central bank. In GoldBod’s audited financial statement for 2025, the precise amount owed to the Bank of Ghana is captured as GH¢3,780,727,736, forming the vast majority of its total trade payables of GH¢3,883,803,022 at year-end. As explicitly noted in the financial statements:"Current liabilities included trade payables of GH¢3,883,803,022, of which GH¢3,780,727,736 relates to amounts payable to the Bank of Ghana under the Domestic Gold Purchase Program.
Crucially, this multi-billion Cedi figure does not reflect a single isolated transaction or lost sum, but rather the net accumulation of numerous daily market transactions and settlement adjustments throughout the year. On several occasions in 2025, GoldBod exceeded its expected delivery targets.
For instance, on June 26, 2025, GoldBod delivered gold valued at GH¢5.28 billion(weighing 3,579.36 kg) against an expected target of GH¢1.63 billion, generating a massive single-day over-supply of GH¢3.64 billion. Similar over-supplies occurred on August 1—when gold worth GH¢4.13 billion was supplied against an expected GH¢2.73 billion—and on October 24, when deliveries reached GH¢3.84 billion against an expected GH¢1.59 billion.
Conversely, significant under-supplies were recorded in other weeks. On August 22, GoldBod supplied gold worthGH¢569.40 million against an expected GH¢2.02 billion,leaving an under-supply of GH¢1.47billion.Further fluctuations occurred in September, including a September 15 delivery of GH¢1.76 billion against an expected GH¢2.49 billion.
In addition to supply variances, the report highlights dates where financial inflows were recorded without corresponding gold deliveries attached during that specific entry. For example, inflows of GH¢500 million on April 24 and another GH¢500 million on April 30 had no gold deliveries recorded against them. Similar entries appeared on May 2 (GH¢917.96 million) and May 5 (GH¢466.68 million).
Towards the end of the year, an expected supply of GH¢1.14billion on December 23 had no matching gold delivery, while inflows of GH¢2 billion on December 30 and another GH¢2 billion on December 31 were recorded without immediate gold supply entries. December demonstrated how rapidly these figures could shift: a major over-supply of GH¢1.37 billion on December 16 was followed three days later by an under-supply of GH¢544.48 million on December 19, before ending with further substantial over-supplies on December 24.
Taken together, these cumulative settlement differences across 2025 explain how the GH¢3.78 billion payable position was established.
GoldBod’s 2025 financial and trade report provides crucial transparency into Ghana’s domestic gold purchasing mechanism. While the GH¢3.78 billion net supply gap represents a substantial liability payable to the Bank of Ghana, a closer look at the transaction history reveals a dynamic trade relationship characterized by continuous over-supplies, under-supplies, and settlement timing differences.
As Ghana continues to leverage its mineral wealth to back foreign reserves and support the economy, tracking these key state trade reports remains essential.
Comments (0)
No comments yet. Be the first to share your thoughts.